A contract read against its side letter.
Aurelia Medical Technologies agrees a five-year diagnostics platform contract with Northmere Health Group, with no termination for convenience. A side letter signed the same day gives Northmere a way out. Alit read the agreement, the side letter and the committee minutes together, and the revenue accounting followed the documents that bind.
IFRS 15 · IFRS 16 · IFRS 9 · IAS 37
8 pages
Platform agreement
VelaAI Enterprise Diagnostics Platform Agreement, executed 15 December 2027. A five-year Initial Term from 1 January 2028 to 31 December 2032, a £600,000 implementation fee, a £1,800,000 annual platform and support fee billed in advance, and a usage fee of £3.00 per completed diagnostic study.
3 pages
Committee minutes
Aurelia’s Commercial Committee approves offering Northmere a unilateral right to terminate for convenience with effect on or after 1 July 2029, and requires the side letter to override the agreement to the extent of any inconsistency.
2 pages
Side letter
Signed with the agreement. Northmere may terminate for convenience, with no termination charge, with effect no earlier than 1 July 2029. Prepaid fees for later periods are refunded, and the side letter prevails where the two documents conflict.
How long is the contract for the purposes of IFRS 15? The agreement and the side letter give different answers.
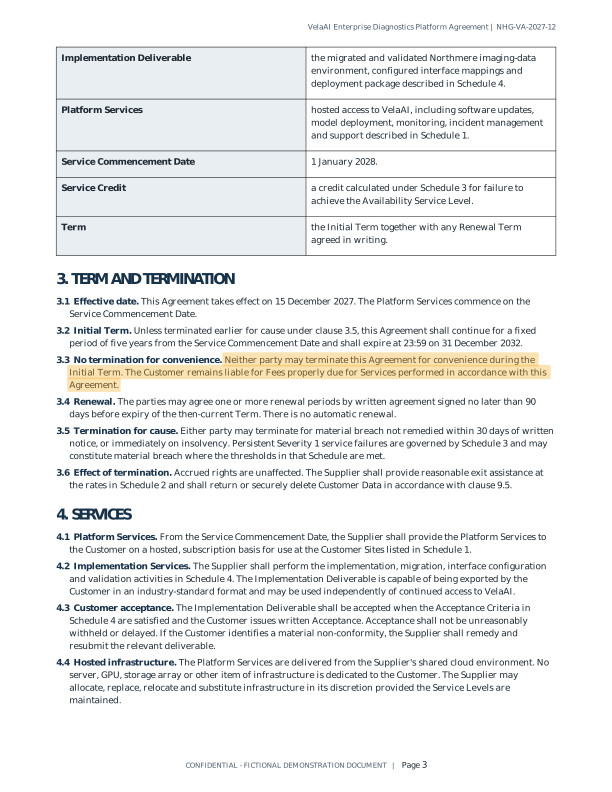
Platform agreement, clause 3.3
“Neither party may terminate for convenience during the five-year Initial Term.”
Side letter, clause 1.1
“Notwithstanding clause 3.3 of the Agreement, Northmere may terminate the Agreement for convenience by written notice, provided that the effective date of termination is not earlier than 1 July 2029.”
The side letter prevails over clause 3.3 under the agreement’s own order of precedence (clause 1.4), and it carries no termination charge. Under IFRS 15.11 the contract term is the period of enforceable rights and obligations: 1 January 2028 to 30 June 2029, eighteen months rather than five years.
Fixed consideration at inception is therefore £600,000 + (18/12 × £1,800,000) = £3,300,000, not £9,600,000. The half of the 2029 annual fee that covers service after 30 June 2029 is refundable on termination. Continuing beyond that date is an option for Northmere on the same terms; at a price that reflects standalone selling price it is not a material right. Collectability is assessed for the 18-month term.
IFRS 15.11
IFRS 15.9(e)
IFRS 15.B40
As written
Enforceable under IFRS 15
Contract term
1 Jan 2028 to 31 Dec 2032
1 Jan 2028 to 30 Jun 2029
Fixed consideration
£9,600,000
£3,300,000
Nine further matters, each graded by impact and cited to the paragraph it rests on.
High impact
Implementation is a separate performance obligation
The implementation deliverable is exportable and usable on its own, so it is distinct from the hosted service. It is satisfied at a point in time on written Acceptance, scheduled for 31 March 2028, because none of the over-time criteria is met.
IFRS 15.27-29
IFRS 15.35
IFRS 15.38
Medium impact
Milestone billing does not decide when control transfers
The £480,000 of milestone invoices raised before Acceptance is a contract liability until then, and the full £600,000 is recognised on Acceptance. Annual fees billed in advance are released as the service is provided.
IFRS 15.105-107
High impact
Usage fees are variable consideration
Volumes cannot be forecast at inception. If the fee relates specifically to each day’s service it is allocated to that period; otherwise estimated usage over the term to 30 June 2029 enters the transaction price, subject to the constraint.
IFRS 15.85
IFRS 15.B16
Medium impact
Service credits reduce the transaction price
Credits are estimated and constrained at inception rather than provided for under IAS 37. The maximum is £30,000 a month, up to £540,000 across the enforceable term.
IFRS 15.50-51
Medium impact
The additional site option
Whether the £75,000 site fee gives Northmere a material right depends on how it compares with the standalone selling price charged to comparable customers, which the reviewer confirms.
IFRS 15.B39-B43
Routine
No significant financing component
Each annual prepayment covers services delivered within twelve months, so the practical expedient applies and no financing component is recognised.
IFRS 15.60-62
IFRS 15.63
Medium impact
Not a lease
The service runs on shared infrastructure over which Aurelia holds an unrestricted, practical right of substitution, so there is no identified asset and the arrangement is a service contract.
IFRS 16.B13-B14
Medium impact
Expected credit losses
The simplified lifetime approach applies to receivables, including invoices raised before the related revenue is recognised. Concentration on a single customer drives the assessment.
IFRS 9.5.5.15
Medium impact
Onerous contract test
Aurelia cannot exit, and pricing is fixed for as long as Northmere continues, up to 31 December 2032. The contract is tested at each reporting date, and only a loss identified by the test is provided for.
IAS 37.66-69
The reviewer moves the contract into a treatment, and the same reading carries through to the journals, the disclosures and the memo.
Aurelia, Northmere and the documents in this example are fictional, and the figures are illustrative. It is not accounting advice.