A step acquisition under IFRS 3.
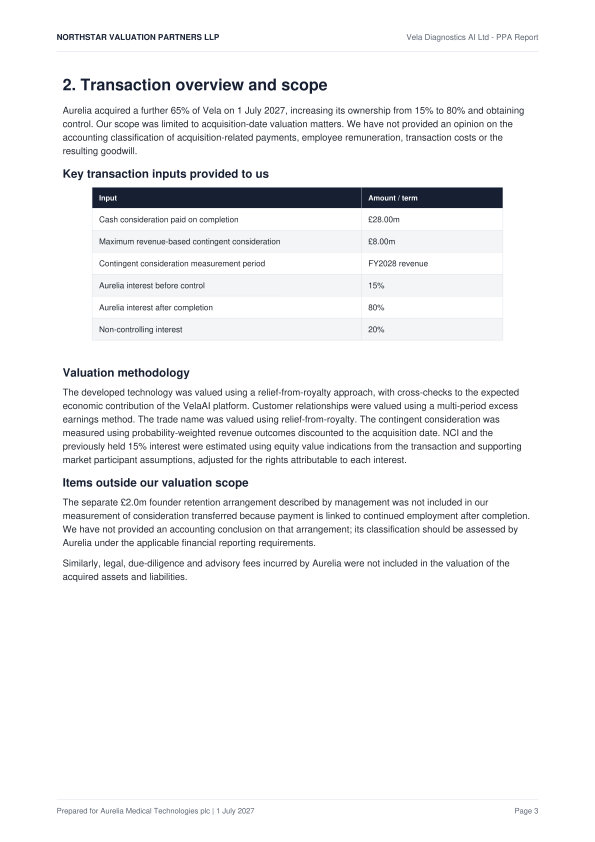
Aurelia Medical Technologies plc already holds 15% of Vela Diagnostics AI Ltd. On 1 July 2027 it buys a further 65% for £28.0m in cash and a revenue-based earn-out, and takes control. This is how the accounting was worked through, from the documents to the memo.
IFRS 3 · IFRS 13 · IAS 36 · IAS 12 · IAS 19
Acquisition date
1 July 2027. Aurelia moves from 15% to 80% of the voting rights and obtains control.
Cash consideration
£28.0m, paid on completion.
Contingent consideration
Up to £8.0m on Vela’s 2028 revenue, payable to the sellers. Fair value at acquisition £5.2m.
Previously held interest
15%, held at fair value through profit or loss. Carrying amount £4.8m, acquisition-date fair value £6.0m.
Non-controlling interest
20%. Fair value £9.0m from the independent valuation.
Founder retention payment
£2.0m to Dr Sen on 30 June 2028 if she is still employed, forfeited on any earlier departure.
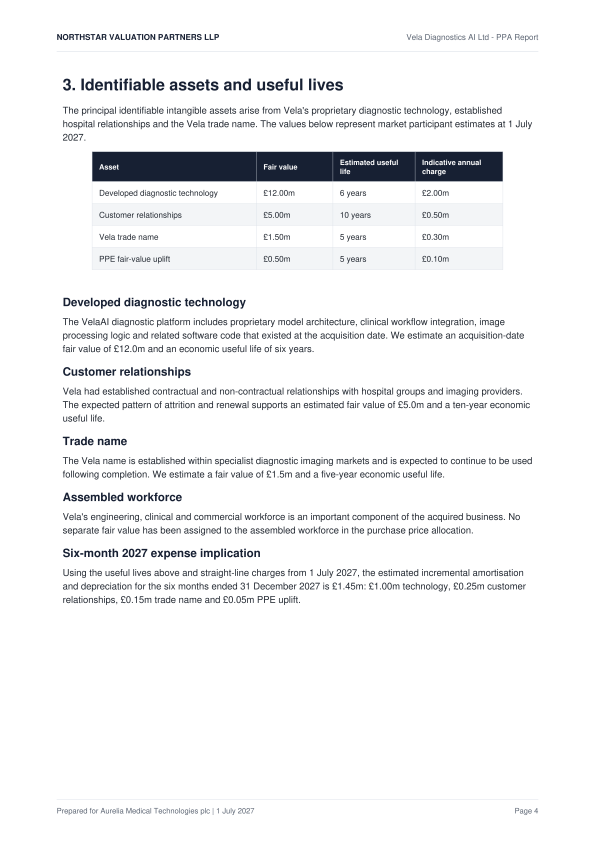
Identifiable assets
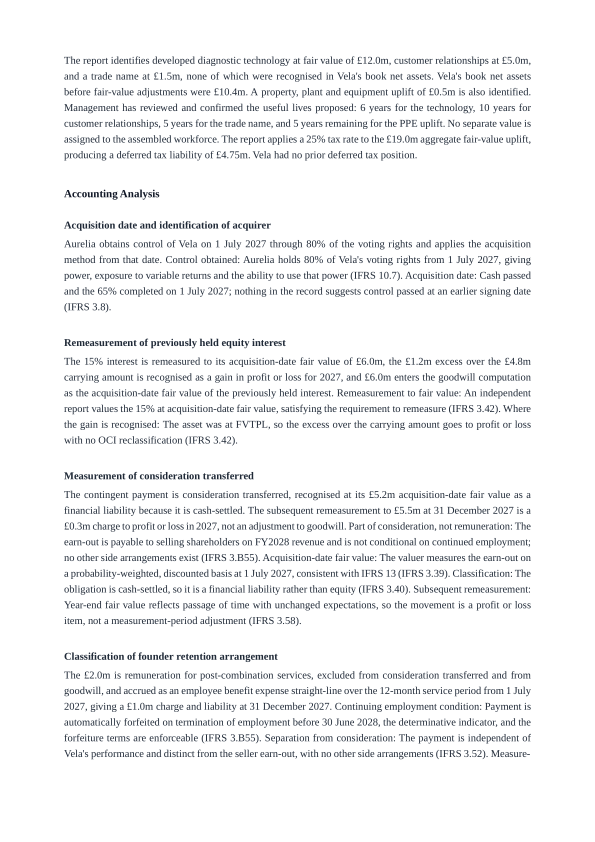
Book net assets £10.4m. Technology £12.0m, customer relationships £5.0m and trade name £1.5m, none previously recognised, and a £0.5m uplift to property, plant and equipment.
Advisory costs
£1.1m of legal, due diligence and advisory fees.
Alit set out thirteen matters for the reviewer: one judgement, one estimate, one election and ten applications of the standard. Five of them carry most of the result.
Election
Measuring the 20% non-controlling interest
Fair value or a proportionate share of Vela’s net identifiable assets: both are permitted, and the choice is made for each combination. Aurelia elected fair value at £9.0m, so goodwill is recognised in full and any later impairment is shared with the non-controlling interest.
IFRS 3.19
IFRS 13.9
Application
Remeasuring the previously held 15%
The 15% is remeasured to its acquisition-date fair value of £6.0m. The £1.2m excess over its £4.8m carrying amount is a gain in profit or loss, and as the holding was at fair value through profit or loss there is nothing in other comprehensive income to reclassify. The £6.0m then enters the goodwill calculation.
IFRS 3.42
Application
The earn-out
The earn-out is paid to the sellers on Vela’s revenue whether or not anyone stays employed, so it is consideration: a financial liability at its £5.2m acquisition-date fair value. The year-end remeasurement to £5.5m is a £0.3m charge to profit or loss, not an adjustment to goodwill.
IFRS 3.39
IFRS 3.40
IFRS 3.58
Application
The founder’s retention payment
Dr Sen forfeits the £2.0m if she leaves before 30 June 2028, so it pays for future service rather than for Vela. It is excluded from consideration and goodwill and accrued over twelve months: £1.0m by 31 December 2027.
IFRS 3.B55
IAS 19.11
Judgement
Allocating goodwill to cash-generating units
Two positions were argued: allocate all of the goodwill to Vela, or spread it across Vela and existing Aurelia units expected to benefit from the synergies. The reviewer chose Vela as a single cash-generating unit: it is a discrete business, management monitors the goodwill at that level and the synergies are expected to arise within it.
IAS 36.80
Goodwill on a full basis, with net identifiable assets stated after deferred tax at 25% on the fair-value uplifts. Figures in £m.
Goodwill at 1 July 2027
£m
Cash consideration
28.00
Contingent consideration at fair value
5.20
Non-controlling interest at fair value
9.00
Previously held 15% at fair value
6.00
Less net identifiable assets
(24.65)
Goodwill
23.55
Net identifiable assets
£m
Book net assets
10.40
Developed technology
12.00
Customer relationships
5.00
Trade name
1.50
Property, plant and equipment uplift
0.50
Deferred tax at 25% on £19.00m of uplifts
(4.75)
Net identifiable assets
24.65
1 July 2027, as drafted for the reviewer. The memo carries five more: the remeasurement gain, the advisory costs, the founder accrual, the earn-out remeasurement and the non-controlling interest’s share of profit.
Account
Dr (£)
Cr (£)
Net assets acquired at existing carrying amounts
10,400,000
Intangible assets: developed diagnostic technology
12,000,000
Intangible assets: customer relationships
5,000,000
Intangible assets: Vela trade name
1,500,000
Property, plant and equipment: fair-value uplift
500,000
Goodwill
23,550,000
Deferred tax liability
4,750,000
Cash
28,000,000
Contingent consideration liability
5,200,000
Non-controlling interest
9,000,000
Investment in Vela at fair value
6,000,000
Total
52,950,000
52,950,000
Each figure in the memo leads to what it rests on. Select an underlined sentence to open the valuation report or the reviewer’s judgement behind it.
Aurelia, Vela and the other companies in this example are fictional, and the figures are illustrative. It is not accounting advice.